Lending with Maggie B. Hopkins
Home Loans in the Sacramento Region, Shopped Across Approved Lenders
I shop your loan across a network of approved lenders and show you all of the math, in plain language and with no pressure to decide.
Maggie B. Hopkins, NMLS #349517 · Surroundings NMLS #2528307
5.0 from 28 Google reviews. Read them →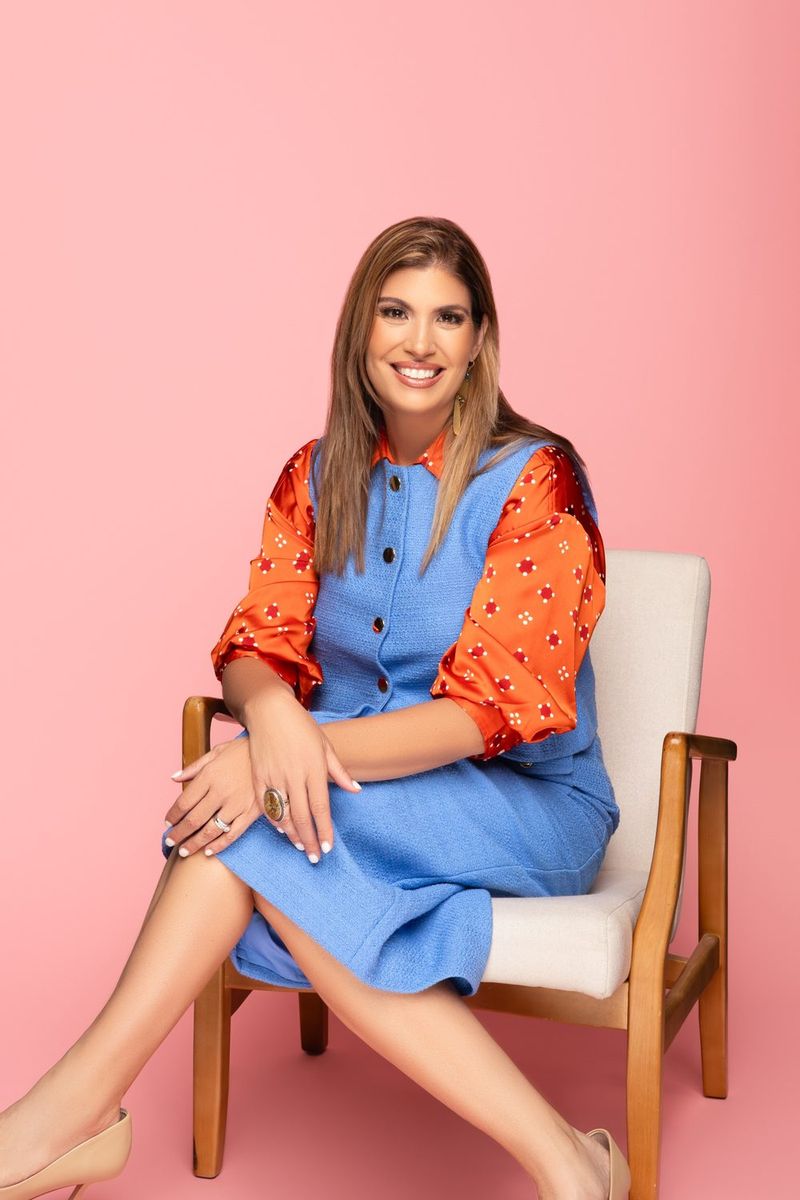
- 2003Originating home loans since
- $100M+In home loans funded
- 5.0From 28 Google reviews
- VACertified VA Loan Specialist, and a Reverse Mortgage (HECM) Lending Specialist
How I shop your loan
One application. A network of approved lenders. You see every number.
I take your goal to a network of approved lenders, line the offers up side by side and walk you through all of the math before you choose.
- YouYour goal, your budget, your timing
- MaggieYour mortgage broker
- A network of approved lendersOffers lined up side by side
- The loan that fits youYour choice, with all of the math
You see all the math: rate, fees and cash to close, for every option.
A bank, or a broker
One bank’s menu, or a network of approved lenders.
Maggie B. Hopkins, mortgage broker, NMLS #349517
At a single bank: who shops
A bank's loan officer can offer only that bank's programs and that bank's pricing.
With Maggie: who shopsMaggie looks at a network of approved lenders for the same borrower and the same home.At a single bank: the math
One lender's Loan Estimate.
With Maggie: the mathLoan Estimates from several approved lenders for the same loan, and Maggie walks you through them.At a single bank: your options
One bank. One set of rates and programs.
With Maggie: your optionsA hand-picked selection of banks and lenders, each with different rates and programs, chosen for your loan.A mortgage broker or bank without real estate
A lender without real estate experience deals only with pricing.
With Maggie: real estate experienceMaggie is a real estate broker and a mortgage broker, so she sees the whole picture from both sides, not only the pricing.
The loans I do
Pick the one you came for.
- Purchase loansLoans for buying a home, shopped across a network of approved lenders and planned alongside the offer.See how it works →
- RefinanceChange your rate or your term, or take cash out, with the break-even math shown first.See how it works →
- Home equity line (HELOC)Borrow against your equity as you need it, with the draw and repayment periods explained up front.See how it works →
- Reverse mortgage (HECM)General information on FHA-insured reverse mortgages for borrowers 62 and older, to stay or to buy.See how it works →
- VA loansVA-backed purchase and refinance loans from a Certified VA Loan Specialist, shopped across lenders.See how it works →
Every loan topic, from FHA to construction loans
Loans for buying a home
Refinancing and your equity
Reverse mortgages, in depth
Self-employed borrowers and investors
Building, modular and manufactured homes
How mortgages work
Behind on payments, short sales and credit
Maggie shops rates and programs at multiple banks
Use us for your loan, your home, or both.
Hi, I’m Maggie. I have been originating home loans since 2003. I am a real estate broker and a mortgage broker, so I look at your move from both sides.
I shop rates and programs at multiple banks and show you all of the math. You don’t get one estimate; you get a full view of every option, side by side. Then I help you pick the loan that is most cost-efficient for you and fits your credit profile and your property best. Use us for your loan, your home, or both. Most clients choose both because it is a one-stop shop, with your loan and your home planned together, in plain language and with no pressure to decide.
- Your loanI shop it across a network of approved lenders, whoever helps you with the house.
- Your homeBuy or sell with Surroundings, and bring any lender you like.
- Most clients choose thisBoth, one teamYour loan and your home planned together, on one calendar, in plain language.
Run your numbers
What would your monthly payment be?
Change any number and the payment updates, with property tax, insurance, HOA dues and mortgage insurance included.
- Principal and interest$400,000 over 30 years at 6.5%$2,528.27
- Property tax$6,250 a year$520.83
- Homeowners insurance$1,500 a year$125.00
- HOA duesNone entered$0.00
- Mortgage insuranceNot added at 20% down or more$0.00
- Estimated monthly total$3,174.11
Estimates only. Your actual payment depends on your loan terms, taxes, insurance and approval. The rate above is an example for the math only, not a quote or an offer of credit.
Questions about your loan? Call or text Maggie at (916) 549-3131.
Estimates only. Your actual payment depends on your loan terms, taxes, insurance and approval. Open the full calculator guide.
Not sure where to start?
Take a two-minute quiz.
Nothing is saved or sent. Each one ends with the pages worth reading next.
- What are you trying to do, and which loan fits?Eight quick questions. You'll get the loan types worth reading about first, and why.Take the quiz →
- What's your credit picture?Seven questions about the habits that move a credit score. This isn't your score, but it shows what's helping and what to work on.Take the quiz →
- Are you ready to buy?Six questions. You'll see what's already in place and what to line up next.Take the quiz →
From our Google reviews
What borrowers say.
We've since used her for 2 more property purchases and 2 refinances over the years. Each time she helped us close fully aware all of our options, with a very competitive rate, and on time!
Lina Fenequito, on Google
I have worked with Maggie twice - a refinance and a home sale. She has been fantastic in both cases. Easy to work with and very knowledgeable.
Sarah Hodge, on Google
If you need someone who knows the ins and outs of real-estate and or brokerage, as well as creative options, Maggie is the very best you can get.
James “JB” DeRose, on Google
Questions people ask
Home loans in the Sacramento region, answered.
What does a mortgage broker do for you?
A mortgage broker shops your loan across a network of approved lenders instead of offering one bank's menu. Maggie B. Hopkins is a mortgage broker. She takes your goal, your income picture and the home, then compares what several approved lenders will offer for that same loan. You see real options side by side. Give yourself options.
A bank's loan officer can offer only that bank's programs and that bank's pricing. A broker can look at a network of approved wholesale lenders for the same borrower and the same home. Pricing differs from lender to lender, and the CFPB notes that rates can change daily. Shopping them is the job.
The Consumer Financial Protection Bureau (CFPB) puts it plainly on its page about comparing offers (last modified December 12, 2024). Your best bargaining chip is usually having Loan Estimates from other lenders in hand. Working with a broker means that comparison happens before you pick.
Why does it help that your mortgage broker is also a real estate broker?
At Surroundings, Maggie is a licensed real estate broker and a mortgage broker. That means one call, one team and one plan for the home and the loan. Nothing gets lost in a handoff between an agent and a loan officer who have never met.
The payoff shows up at the moments that matter most. When a seller asks how strong your financing is, the person answering knows your file. When an appraisal comes in low, the same team can talk about the contract and the loan at once. When a repair turns up in inspection, you hear what it means for the price and for the lender in one conversation.
The same is true on the selling side. If you're downsizing and buying the next home, the sale, the purchase and the money can sit on one timeline.
Read more about how home loans work hereClose
Do you have to use Surroundings for your loan?
No. You're always free to use any lender you like, and you can work with us on the real estate side either way. Nothing on the real estate side depends on where you get your loan.
We'd still like the chance to compete for it. Get a quote from us and compare it against anyone. If you have another lender's Loan Estimate, bring it in and we'll go through it with you line by line.
How does pricing on a mortgage work?
Every loan has a rate and a set of costs, and the two move together. The CFPB explains on its page about no-cost loans (last reviewed April 3, 2024) that a lender can cover your closing costs by charging a higher interest rate and giving you a credit. It can also add the costs to your loan amount. Either way the costs still exist. You pay them over time instead of at closing.
That trade-off is where people get confused, so we show you the math. For each option you can see the rate, the costs at closing and any credit. You also see what that choice looks like over the years you expect to keep the loan. Then you choose.
Every lender must give you a Loan Estimate within three business days of your application, according to the CFPB (page last modified August 14, 2024). All lenders use the same form, which helps you compare offers. Our mortgage calculator lets you test a monthly budget with tax and insurance included before you talk to anyone.
Are you asking the right questions about your loan?
Many of the most useful questions about a loan never get asked. Before you sign, ask these, and ask every lender you compare:
- Rate and fees. What is the rate if I pay more in fees up front? What is it if I pay less?
- Paying fees back. If I pay fees up front, how long will it take for the lower payment to make that money back?
- Cost while I own the home. How much will this loan cost me over the years I actually plan to stay?
- Cost over the full term. What does it cost in total over 30 years?
- Buying down the rate. Should I pay up front to lower my rate, and how much could I save if I do?
We answer each of these in dollars for every option we show you.
What is a rate buy-down, and which kind fits you?
A buy-down means paying money up front to lower your interest rate. There are two kinds, and the difference matters for your flexibility later.
- Permanent buy-down. You pay to lower the rate for the whole life of the loan, for example on a 30-year fixed loan. The trade-off: if rates fall later and you refinance, the money you paid to buy down the rate doesn't come back.
- Temporary buy-down. Money set aside up front lowers your payment for the early years of the loan, then the payment steps up to the full rate. Ask the lender what happens to any money not yet used if you refinance or sell early. On many loans it goes toward your loan balance, but get the lender's answer in writing.
Which one makes sense depends on how long you plan to keep the loan and where you think rates are heading. We show you both side by side so you can decide.
How do you get started?
Start with the loan options form. Tell us what you're planning and when, and Maggie will look at it and get back to you within 2 hours. Would you prefer to talk first? Call Maggie's cell at (916) 549-3131 or use the contact page.
A first conversation is about your goal, not paperwork. What are you buying or refinancing? What monthly budget feels right? How long do you plan to keep the home? From there we can tell you which documents to gather and which loan types are worth comparing.
We work across the region, from Sacramento and Elk Grove to Roseville, El Dorado Hills and Davis.
A different way to exercise inclusivity: in practice
As part of our dedication to this mission, we bring to the table not just a passion for real estate but also the financial lending expertise that empowers us to guide you through the intricate process of finding the right home. We believe in creating inclusive communities, and we are committed to ensuring that everyone has access to real estate knowledge.
Qualified Mortgage (QM)
A Qualified Mortgage is a category of loans that have certain, more stable features that help make it more likely that you’ll be able to afford your loan. These loans are defined by the Consumer Financial Protection Bureau (CFPB) and are designed to meet requirements that prevent lenders from offering loans with risky features such as:
- Excessive upfront points and fees (total points and fees cannot exceed 3% of the total loan amount for loans over $100,000).
- Interest-only periods, where payments are not made towards the principal balance.
- Negative amortization, where the loan principal increases over time.
- Balloon payments (lump-sum payments typically due at the end of a loan term), except under certain conditions in rural areas.
Why are they called “Qualified”? The term “Qualified” refers to the compliance of these loans with specific guidelines that qualify protections for lenders against borrower lawsuits. Essentially, a QM follows guidelines that are believed to reduce the likelihood of borrower default, making them a safer and more “qualified” investment for lenders.
Non-Qualified Mortgage (Non-QM)
Non-Qualified Mortgages are those that do not conform to the CFPB’s rules. They include loans that are geared towards borrowers with unusual or variable income streams, higher levels of risk, or those who require flexibility in terms that don’t meet QM criteria. These might include:
- Loans with features like interest-only payments, high loan-to-value ratios, or terms that exceed 30 years.
- Loans for borrowers with non-traditional income or those who prefer asset-based lending over income verification.
- Loans that exceed the points and fees thresholds established for Qualified Mortgages.
Why are they called “Non-Qualified”? They are called “Non-Qualified” because they do not meet the stringent criteria set forth by the CFPB to qualify for the safe harbor protections offered to lenders and borrowers under the QM rules. These loans typically present a higher risk and are often priced to reflect that risk.
Senior mortgage solutions
Certified expertise: senior & probate real estate
Navigate probate with ease or learn how to avoid it altogether with our certified senior real estate expertise. At Surroundings, we simplify the complexities, ensuring a smooth & sensitive approach to your real estate needs.
Mortgage solutions: financing your future
Explore tailored mortgage solutions with us, from forward and reverse mortgages to home equity lines of credit (HELOC) and creative financing options. Our team’s expertise ensures you secure financing that perfectly fits your unique needs, providing financial comfort and ease.
Read more: Debunking reverse mortgage myths and new credit score models for mortgages in California.
Frequently Asked Questions
Is a mortgage broker the same as a lender?
No. A lender funds the loan, and a mortgage broker shops your loan across a network of approved lenders and manages it through closing. Maggie B. Hopkins is a mortgage broker.
Do I have to use your lending to work with you on a home?
No. You can use any lender you like and still work with us on the real estate side. We'd like the chance to quote your loan, and the choice is yours.
Can you tell me today's rate?
No, not on a web page. Rates change often and depend on the loan, the home and your file, so we quote real options once we know your situation. The loan options form is the place to start.
Which areas do you lend in?
We work with borrowers in Sacramento, Placer, El Dorado and Yolo counties. Ask us about a home outside that area and we'll tell you what we can do.
Should I buy down my interest rate?
It depends on how long you'll keep the loan. Ask how long it takes for the lower payment to make back what you paid up front. If you're likely to sell or refinance before then, a buy-down may not pay off. We show you the math for each option.
What is the difference between a permanent and a temporary buy-down?
A permanent buy-down lowers your rate for the whole loan, and that money doesn't come back if you refinance later. A temporary buy-down lowers the payment only for the early years. Ask the lender what happens to unused buy-down money if you refinance or sell early.
Do you offer USDA, construction or bank statement loans?
Yes, we arrange them through lenders that offer them, along with modular, mobile home, DSCR and hard money loans. See our pages on Non-QM loans and on USDA, construction and mobile home loans.
How do I compare your quote with another lender's?
Compare the Loan Estimates side by side. Every lender uses the same federal form. You can line up the rate, closing costs, credits and cash to close for the same loan amount.
Talk to Maggie
Ask Maggie about a loan.
Maggie shops your loan across a network of approved lenders and answers every loan question herself.
Talk to Maggie directly: cell (916) 549-3131 (text or call) · maggie@loveyoursurroundings.coMaggie B. Hopkins, NMLS #349517 · Surroundings NMLS #2528307
Loans are arranged through Maggie B. Hopkins, NMLS #349517 · Surroundings NMLS #2528307. This is not a commitment to lend. All loans subject to credit approval and property qualification. Equal Housing Lender.